
Ideas for a better investment
Mortgage Note Due Diligence: The Ultimate Guide
Discover how to perform effective mortgage note due diligence. Get practical steps for valuation, borrower review, payment analysis, & risks.

31 min read

Before purchasing a mortgage note, there’s one step you simply can’t afford to skip: mortgage note due diligence. A single overlooked detail—an incomplete chain of title, inflated property valuation, or hidden tax lien—can transform a promising investment into a costly mistake.
Whether you’re evaluating your first note or scaling a portfolio of performing and non-performing assets, mastering mortgage note due diligence is the difference between consistent returns and preventable losses. This comprehensive guide covers the essential process—from property valuation and borrower assessment to payment analysis and offer calculations—giving you practical tools to make informed decisions and reduce investment risk.
In this guide, you’ll learn:
- A step-by-step due diligence process for evaluating mortgage notes
- Critical risk factors that determine investment viability
- How to define your buy box and initial screening criteria
- Essential legal considerations: bankruptcy, foreclosure procedures, IRS liens
- State-specific requirements and redemption rights
- Common mistakes that cost investors thousands (and how to avoid them)
- Tools and resources for efficient due diligence
- How Paperstac streamlines document verification and closing
📋 Download Your Free Due Diligence Checklist
Get our comprehensive PDF checklist to follow along with this guide and use for every deal!
Download Free Checklist →🎥 Watch: Mortgage Note Due Diligence Essentials
Prefer video? Watch our complete Note Investing Due Diligence Playlist from the Paperstac Podcast, where we break down every critical step.
Featured Episode:

Running Due Diligence on Mortgage Notes
What Is Mortgage Note Due Diligence?
Due diligence is the investigation process that note investors perform before purchasing real estate-backed debt. This thorough examination of financial records, property details, borrower creditworthiness, and legal documentation ensures your investment is sound and profitable.
For mortgage note investing, due diligence helps identify potential risks and opportunities while protecting your capital. Whether you’re evaluating performing notes for passive income or non-performing notes for profitable workouts, mastering this process is essential for success in the note investing business.
💰 Understanding Mortgage Note Due Diligence Costs
A basic due diligence package that includes a BPO, O&E report, and standard title report might cost between $300 and $500, while a more thorough investigation involving detailed legal or collateral reviews can cost much more. Consider these costs as essential insurance on your investment—they’re significantly less expensive than purchasing a problematic note.
Initial Mortgage Note Due Diligence: Defining Your Buy Box
Initial due diligence for note investing will differ from one investor to the next. Before submitting initial bids, experienced investors hit key components of their due diligence checklist. Newer investors may conduct more extensive research during this early period. Think of this as defining your buy box—the criteria that determine which notes deserve deeper analysis.
Basics of the Initial Screening Process
Here’s a straightforward approach for initial screening before making offers:
Eliminate Non-Qualifying States
Cross off any states you don’t want to invest in based on foreclosure laws, timelines, or market conditions. Some investors avoid judicial foreclosure states like New York or New Jersey due to lengthy, costly processes.
Filter Cities & Markets
Cross off cities that don’t meet your criteria: low population, high vacancy rates, negative growth rates, or declining markets.
Screen Property Characteristics
Eliminate properties that don’t meet basic criteria: built before 1950, less than 3 bedrooms, severe condition issues, or undesirable property types.
Evaluate Note Metrics
Cross out notes that don’t fit your strategy: problematic payment history, UPB too high relative to value, unfavorable interest rates, or unclear servicing status.
Conduct Deeper Analysis
For notes that pass initial screening, take additional due diligence steps based on your experience level and comfort with the asset.
Key Risk Factors in Mortgage Note Investing
🏠 Underlying Collateral Type
Due diligence varies significantly based on property type:
- Single-Family Residential: Easiest to value and liquidate
- Multi-Family: Requires income analysis
- Commercial Property: More complex valuation
- Vacant Land: Highest risk, hardest to monetize
💰 Equity Position
Adequate equity protects your investment:
- Strong equity = lower risk of loss
- Calculate Loan-to-Value (LTV) ratio
- Ideal LTV: 65-75% or lower
- Second liens require even more equity cushion
📍 Property Location
Location affects both value and exit options:
- Desirable areas maintain value better
- Check foreclosure laws by state
- Evaluate neighborhood trends
- Consider property marketability
👤 Borrower’s Ability to Pay
Payment history reveals future likelihood:
- Long payment history = higher reliability
- Recent hardships may be temporary
- Verify employment and income stability
- Review debt-to-income ratios

⚠️ Important Tip: State Foreclosure Laws
Knowing a state’s foreclosure process is a critical piece of your due diligence. You may write off a state completely because of lengthy and costly foreclosure timelines. For example, some note investors don’t purchase properties in New York or New Jersey because of the extended judicial foreclosure processes.
Judicial states (shown in blue) require court supervision for foreclosures, typically taking 6 months to 3+ years. Non-judicial states (shown in gray) allow faster foreclosure processes, often 60-120 days.
The Complete Step-By-Step Mortgage Note Due Diligence Process
Once a note passes your initial screening, it’s time for comprehensive due diligence. Here’s the detailed process successful note investors follow:
Step 1: Establishing Property Value
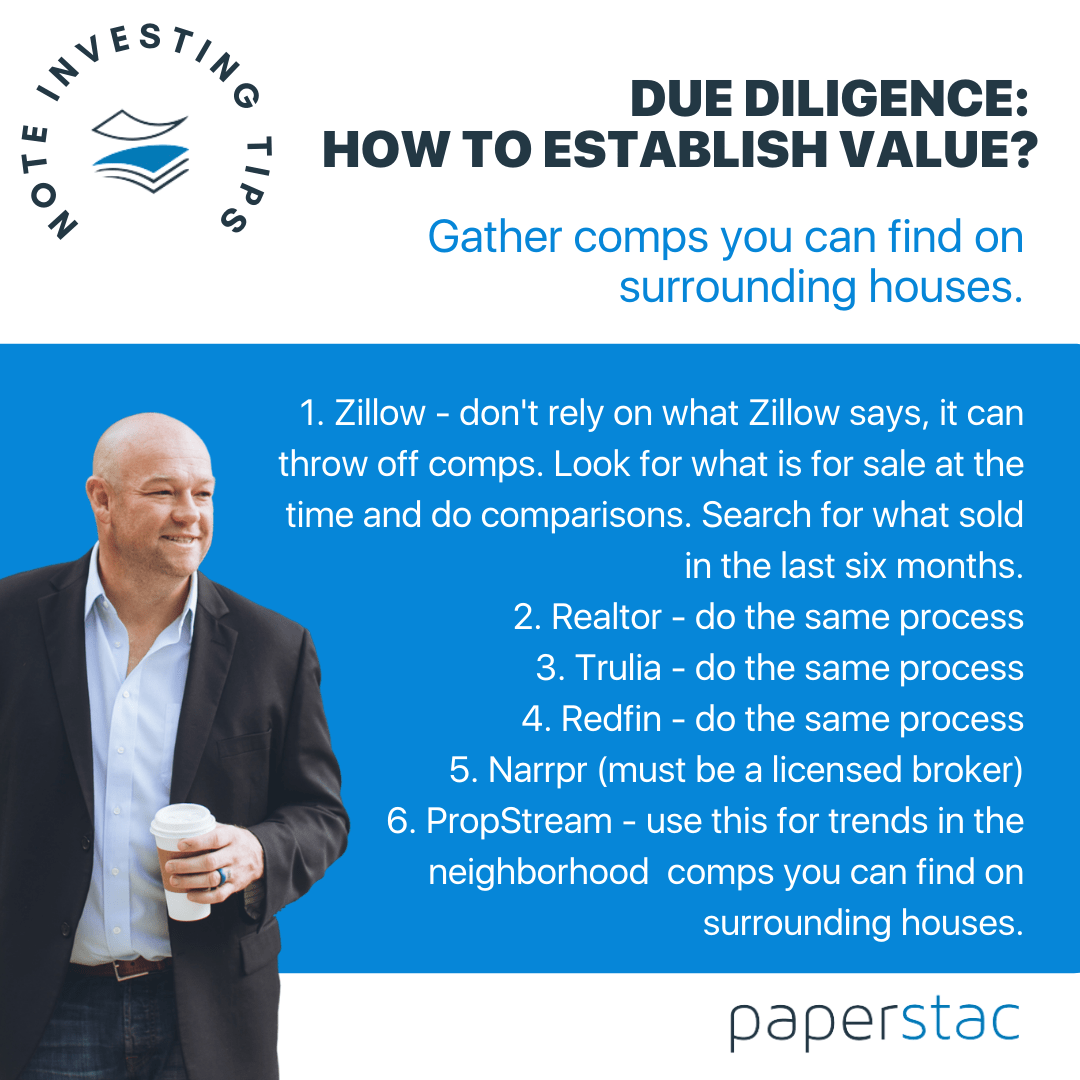
The first thing you want to do is have an idea of value. Value is one of the most important factors, because at the end of the day, your investment is backed by assets that should have adequate value.
You don’t want to buy a note worth around $100,000 in principal balance when the house is only worth $75,000. If you base your purchase solely on the principal balance, it could come back to hurt you.
What is an “Armchair Value”?
Start by getting an armchair value—an initial valuation using online resources before ordering professional reports. This means researching values from multiple sources to establish a realistic range.
The following websites are great resources for gathering comparable sales data to help you establish value when performing note investing due diligence:
1. Zillow
Don’t rely solely on Zillow’s Zestimate—it can be inaccurate. Look for what’s currently for sale and do comparisons. Search for recent sales in the last six months.
2. Realtor.com
Follow the same process—compare active listings and recent sales.
3. Trulia
Another source for comparative market analysis. Do the same process.
4. Redfin
Provides additional market insights and trends. Do the same process.
5. NARRPR
MLS access for licensed real estate brokers. Must be a licensed broker to access.
6. PropStream
Excellent for analyzing neighborhood trends and detailed property data.
Key Valuation Tips
- Focus on ranges rather than single numbers. Think in terms of ARV (After Repair Value).
- Look for As-Is Value: This is not an exact science. Assume that if the outside looks bad, the inside will too (and vice versa).
- Use Proxy Pic for drive-by photos to understand how the homeowner values their home (emotional equity). Do this at the time of making an indicative offer.
- Analyze current competition: Look at what your competition is right now. You want to know what’s going on in that market.
- Look at market demand: What is the demand like in this area?
- Look at value trends: Are values increasing, stable, or declining?
Remember: You want to have a good idea of value. That’s first and foremost.
Step 2: Reviewing Digital Documents & Collateral Files
Next, when conducting note investing due diligence, review all financial statements and digital documents. The seller should upload to the platform all collateral files including:
- The promissory note
- Mortgage or deed of trust
- Credit report
- Chain of assignments
- Chain of allonges
- Origination files (ideal to have before purchase)
These are all documents you could potentially use in court if enforcement becomes necessary. This documentation forms your legal foundation.
Understanding Note Terminology: Key Parties and Roles
Mortgage note transactions involve specific terminology that can be confusing for new investors. Understanding who owes what to whom is fundamental to evaluating note quality and enforcing your rights.
The Borrower (Debtor)
The person who owes money is referred to by multiple terms:
- Maker: The party who “made” or signed the promissory note
- Mortgagor: In mortgage states, the party who mortgaged the property
- Trustor or Grantor: In deed of trust states, the party who granted the trust
- Debtor or Obligor: Generic terms for the party obligated to pay
The Lender (Creditor)
The person or entity owed money is also known by several terms:
- Payee: The party to whom payment is made
- Mortgagee: In mortgage states, the party holding the mortgage
- Beneficiary: In deed of trust states, the beneficial owner of the debt
- Creditor or Obligee: Generic terms for the party owed money
The Trustee (Deed of Trust States Only)
In deed of trust states, a neutral third party called the trustee holds legal title to the property until the debt is paid. The trustee has the power to sell the property through non-judicial foreclosure if the borrower defaults.
💡 Pro Tip
When reviewing note documents, verify that the borrower’s name appears consistently across all documents. Variations in name spelling or missing middle initials can create enforcement challenges and title issues later.
Security Instrument Verification Checklist
The security instrument (mortgage or deed of trust) must contain specific elements to be enforceable. Missing or incorrect information can render the entire security instrument invalid, leaving you with an unsecured debt.
10-Point Security Instrument Checklist:
Why Recording Date Matters
The recording date establishes lien priority. If multiple liens exist on a property, the first to record generally has first claim to proceeds from a foreclosure sale (with exceptions for property tax liens and some mechanic’s liens). A mortgage recorded on January 1st has priority over one recorded on February 1st, even if the February mortgage has a higher balance. This is called the “first in time, first in right” principle.
🚨 Red Flag Alert
If the security instrument lacks a proper legal description or wasn’t recorded in the correct county, you may not have a valid lien on the property. This makes foreclosure impossible and leaves you with an unsecured debt.
Step 3: Analyzing Payment History & Servicing Notes
Servicing notes reveal potential exit strategies and tell you what’s happening with the loan. Begin by examining the payment history to establish the “story” of the note.
Your Goal: Understand the Borrower
If you can obtain 24 months or more of payment history, you’ll get a good picture of the borrower’s payment cadence. Look for patterns:
- Past dues or missed payments
- Consistency or inconsistency in payment timing
- Payment amounts (full, partial, late fees)
When you spot patterns, jump into the servicing notes to see what happened and why.
What You’re Really Asking:
- For performing notes: Can I set it and forget it, or is this a potential headache?
- For non-performing notes: Do I see exit strategies others might miss because they didn’t read the servicing notes?
Red Flags to Watch For
If the borrower’s debt-to-income ratio seems out of whack—for example, on paper they could afford a $750 payment but records show $950—that’s a red flag worth investigating.
Remember: Servicing notes and payment history are crucial. They tell the story.
📺 Related Video Resources:
Step 4: Verifying Chain of Title & Assignments
Verify There Is a Copy of the Mortgage and Note
It’s essential to verify that copies of the mortgage and promissory note exist. The note is your promise to repay—essentially an IOU. Mortgages are recorded in public records, so there should be documentation.
⚠️ What If the Original Note Is Missing?
If there isn’t an original note, ensure there is a lost note affidavit. Have an attorney in that state review it to confirm it’s valid. Important: Certain states like Maine require the original note. Without it, you cannot move forward with purchasing the asset or foreclosing.
Track Every Transfer
When exercising due diligence, verify you have the original note, then start at the beginning:
- Who originated the note and mortgage?
- Track every transfer with corresponding assignments
- Verify corresponding allonges accompany each transfer
If you don’t have complete documentation, there’s a gap in the assignment chain. If the gap is at the end (near the current seller), discuss with the seller what’s missing.
Critical Questions to Answer:
- Who am I buying this asset from?
- What’s the entity?
- Can I see the assignment going into their entity?
If they’re brokering the note, you may need to have additional discussions. However, a good note investing strategy means seeing a full, complete chain of assignments.
Understanding Foreclosure Procedures: Judicial vs. Non-Judicial
The foreclosure method available in your property’s state directly impacts your investment timeline, costs, and strategy. Understanding these differences before purchase is critical to accurate return calculations.
Non-Judicial Foreclosure (Deed of Trust States)
✅ Advantages
- Faster process: typically 3-6 months from start to sale
- Lower legal costs: $1,500-$3,500 average
- No court involvement required
- Streamlined procedures defined by state statute
- Less opportunity for borrower delays
Non-judicial foreclosure is available in states that use deeds of trust as security instruments. The trustee named in the deed of trust has the power to sell the property at a public auction without court approval, following specific notice requirements defined by state law.
Judicial Foreclosure (Mortgage States)
⚠️ Challenges
- Longer timeline: typically 12-24+ months from filing to sale
- Higher legal costs: $5,000-$15,000+ average
- Requires full court proceedings and judgment
- Borrower has multiple opportunities to delay
- More complex process with strict procedural requirements
- Attorney representation typically required
Judicial foreclosure requires filing a lawsuit, obtaining a court judgment, and conducting a sheriff’s sale under court supervision. This process is mandatory in states that use mortgages as security instruments.
| Feature | Non-Judicial | Judicial |
|---|---|---|
| Timeline | 3-6 months | 12-24+ months |
| Cost | $1,500-$3,500 | $5,000-$15,000+ |
| Court Required | No | Yes |
| Security Instrument | Deed of Trust | Mortgage |
| Complexity | Lower | Higher |
| Attorney Needed | Recommended | Required |
Can I choose which foreclosure method to use?
No, the foreclosure method is determined by your security instrument type and state law. You cannot change the foreclosure method after purchase—it’s determined when the original loan was created.
How foreclosure timelines impact returns:
A 24-month judicial foreclosure means 24 months of property taxes, insurance, maintenance, and lost opportunity cost. If you purchase a $50,000 note on a property with $2,000 annual taxes and $1,500 annual insurance, a 2-year foreclosure adds $7,000 in hard costs alone.
How Bankruptcy Affects Note Investments
When a borrower files bankruptcy, all collection and foreclosure activities immediately stop due to the “automatic stay.” Understanding how different bankruptcy chapters affect your rights is essential to protecting your investment.
Chapter 7 Bankruptcy: Liquidation
⏱️ Timeline: 30-60 Days
If borrower has no equity, stay typically lifted within 30-60 days through motion for relief.
🛡️ Secured Position Protected
Your secured claim survives bankruptcy if properly documented. Lien remains on property even if personal liability is discharged.
📋 Motion for Relief
File motion for relief from stay to continue foreclosure. Courts grant relief when no equity exists or borrower can’t cure default.
Chapter 13 Bankruptcy: Reorganization
⚠️ Impact on Note Holders
- Borrower proposes plan to cure arrearages over 3-5 years
- You receive monthly payments through bankruptcy trustee (minus trustee fees)
- Cannot foreclose while plan is active and current
- If plan fails (70%+ fail), you can resume foreclosure on remaining default
- Interest may or may not accrue on arrearages depending on court and equity position
Chapter 11 Bankruptcy: Business Reorganization
Chapter 11 is typically filed by businesses or individuals with substantial assets. Secured creditors must receive at least the fair market value of their collateral through the reorganization plan.
🚨 Critical: Automatic Stay Violations
Foreclosure sales conducted without proper notice that a bankruptcy was filed are VOID. If you foreclose in violation of the automatic stay, you may face sanctions, damages, and attorney fee awards. Always search bankruptcy records (PACER system) before proceeding with any foreclosure sale.
Step 5: Title Reports & Property Taxes
Order an Owner & Encumbrance (O&E) Report
An O&E report is a crucial tool for note investors conducting due diligence. One of your first steps should be ordering an O&E title report from a title search company after your initial bid is accepted. It typically costs around $90 and is well worth the investment.
What an O&E Report Includes:
- Information on vesting
- Assignments and mortgages
- Federal, state, and local government liens
- HOA encumbrances/liens
- Civil case judgments
- Any foreclosure proceedings
- Property information
- Deed from the current owner
Property Tax Verification
After obtaining the O&E report, research the tax side. You want to verify all property taxes are current and paid.
Information for Note Investors to Check:
Remember: Both title and taxes are critical aspects of mortgage note transactions that should never be overlooked. Tax liens take priority over mortgage liens in most jurisdictions!
IRS Liens & Federal Tax Considerations
Federal tax liens create unique complications for note investors. Unlike state and local liens, IRS liens follow specific federal procedures that can significantly impact your foreclosure timeline and recovery.
🚨 Mandatory 25-Day Notice Requirement
If you’re foreclosing on a lien that’s SENIOR to an IRS lien, you must give the IRS written notice at least 25 days before the foreclosure sale. Failure to provide proper notice can result in the IRS setting aside your foreclosure sale. The notice must be sent via certified mail to the IRS office listed on the tax lien filing.
The 120-Day IRS Redemption Period
Even with proper notice, the IRS has a right of redemption for 120 days AFTER your foreclosure sale. During this period:
- The IRS can reclaim the property by paying your foreclosure sale price plus costs
- You cannot sell or encumber the property
- You must continue paying property taxes and insurance
- Your capital remains tied up in the property
- The IRS rarely exercises this right (estimated <1%) but the risk exists
Lien Priority and Federal Tax Liens
Federal tax liens are filed with county property records and follow specific priority rules:
- IRS Lien Filed After Your Lien: It’s junior to your lien and is wiped out by your foreclosure (but you still must provide notice and respect the 120-day redemption)
- IRS Lien Filed Before Your Lien: It’s senior to your lien and must be paid to clear title
- Property Tax Liens: Generally senior to all other liens, including IRS liens
How to Find IRS Liens:
IRS liens are filed with the county recorder or registry of deeds where the property is located. Your title search should reveal any recorded federal tax liens. Never assume there are no IRS liens—always verify during your title due diligence phase.
State Redemption Rights & Timeline Impacts
Redemption rights allow borrowers to reclaim their property AFTER a foreclosure sale by paying the full amount owed plus costs. These rights exist in approximately 26 states and can significantly impact your holding costs and investment timeline.
How Redemption Rights Work
During the redemption period:
- You hold legal title but cannot sell or significantly modify the property
- The borrower can redeem by paying the full foreclosure sale price plus additional costs
- You must continue paying property taxes and insurance
- The property may remain occupied by the borrower or be vacant
- Your capital is tied up and cannot be redeployed
Redemption Periods by State
| Category | Example States | Period |
|---|---|---|
| No Redemption | Alabama, Alaska, Arizona, California, Colorado, Florida, Georgia, Oregon, Texas, Virginia, Washington | None |
| Short Redemption (30-90 days) | Arkansas, Idaho, Kansas, New Mexico | 30-90 days |
| Standard Redemption (6-12 months) | Illinois, Iowa, Kentucky, Michigan, Minnesota, Wisconsin | 6-12 months |
⚠️ Planning for Redemption Periods
Always research your state’s redemption rights BEFORE purchasing a note. A 12-month redemption period on a property with $3,000 in annual taxes and $1,500 in annual insurance adds $4,500 in holding costs to your investment. Factor this into your purchase price or you’ll significantly underperform your projected returns.
Should I Avoid Redemption States?
Not necessarily. Redemption states can offer opportunities if you price the investment correctly. The key is to factor the redemption period into your holding costs and required return.
Step 6: Getting a Broker Price Opinion (BPO)
Verifying all details—including value—is essential. How do you do that? Reach out to a local real estate agent in the property’s area, or order a BPO (Broker’s Price Opinion).
What is a BPO?
A broker’s price opinion is a real estate broker’s or qualified professional’s determination of property value. Typically performed by a broker knowledgeable about the local housing market, a BPO assigns a dollar amount based on specific property characteristics.
Important: A BPO doesn’t represent official market value or an appraised value, but it provides crucial information about the home’s realistic valuation.
Get Eyes on the Property
A BPO helps you get the most accurate information about a home’s valuation. The agent verifies value and physically views the property, providing you with:
- Photos of the property
- Clearer estimate of value
- Better understanding of the property’s story
This is critical! If the collateral is demolished or severely damaged, it becomes difficult to recover your investment or generate profit. A BPO catches these issues before you commit capital.
Additional BPO Benefits
The BPO provider will also review the Owner & Encumbrance Report or search title (mentioned previously). They verify everything you’re examining and flag any red flags from their title search.
You can choose different title search depths: one owner, two owners, or full foreclosure search. Obviously, more in-depth searches cost more and take longer, so plan accordingly.
Essential Closing Documents Checklist
The closing process for a note purchase requires specific documents to establish your legal ownership and protect your rights. Missing or improperly executed closing documents can create enforcement challenges that cost thousands to correct.
5 Critical Closing Documents:
The original note must be endorsed “payable to the order of [Your Name], without recourse” or have an allonge (attachment) with proper endorsement. The “without recourse” language protects you from prior lender liabilities.
Why it matters: Without proper endorsement, you may not be able to prove ownership and enforce the debt.
A properly executed assignment document that transfers all rights under the security instrument from seller to you. This must be recorded in the county where the property is located to perfect your lien position.
Why it matters: Unrecorded assignments can create title issues and delay foreclosure.
Either a new lender’s policy naming you as insured, or an endorsement to the existing policy showing the change in lender. This protects you against unknown title defects.
Cost: Typically $300-$800 depending on property value.
Full payment history from origination through closing, including dates and amounts of all payments, charges, and credits. This establishes the current balance and any arrearages.
If using a loan servicer, proper transfer documentation and borrower notification as required by RESPA (Real Estate Settlement Procedures Act).
✅ Proper Note Endorsement Example
“Pay to the order of [Your Name/Entity], without recourse.”
Signed by:
[Seller Name]
Date:
[Closing Date]
Why “without recourse” matters:
This language means you’re not responsible for any representations or warranties the seller made to their lender. If there are issues with the original loan origination, underwriting, or documentation, those remain the seller’s responsibility, not yours.
⚠️ Do I Need an Attorney to Close?
While not legally required in all states, using an experienced real estate or note attorney is strongly recommended, especially for your first few transactions. An attorney ensures proper document execution, identifies potential legal issues, and protects your interests. The $1,000-$2,500 you spend on legal review is minimal compared to the cost of fixing improperly documented transactions later.
Calculate Your Maximum Offer
Now that you’ve completed your due diligence, use this calculator to determine your maximum purchase price. This tool uses three proven pricing methods and recommends the most conservative (safe) approach.
Paperstac Max Offer Calculator
- Method 1: Yield-Based Present Value
- $69,477
- Method 2: ITV Collateral Cap
- $112,500
- Method 3: Foreclosure Exit Analysis
- $76,800
$69,477Recommended Max Offer · Most conservative of the 3 methods
- Current ITV
- 66.7%
- Target ITV
- 75%
- Risk Level
- Low
- Equity Cushion
- $80,523
This calculator provides estimates based on your inputs. Always conduct thorough due diligence and consult with qualified professionals before making investment decisions. Results assume simplified scenarios and may not account for all deal-specific factors.
How the Calculator Works:
Method 1: Yield-Based PV - Calculates what you should pay to achieve your target yield based on the monthly payment stream.
Method 2: ITV Cap - Limits your purchase based on property value (75% for performing, 65% for re-performing, 55% for NPL).
Method 3: Foreclosure Exit - Assumes worst case (foreclosure + REO sale) and works backward from net recovery with 60% safety margin.
Your max offer is the MINIMUM of all three methods - this ensures you're protected even in the worst-case scenario.
💡 Pro Tips for Using This Calculator
- Always use current BPO values, not Zillow or AVM estimates
- Be conservative with repair estimates (add 20% buffer)
- Research your state's foreclosure timeline and costs
- Leave room below max offer for negotiation (bid 5-10% lower)
- Adjust target yield based on risk (higher risk = higher yield)
Common Red Flags in Note Investing
Recognizing warning signs early can save you from costly mistakes. Here are critical red flags to watch for during your due diligence process:
🚩 Incomplete Documentation
- Missing assignments in chain of title
- No original promissory note or lost note affidavit
- Gaps in payment history
- Missing servicing notes or contact records
🚩 Property Issues
- Significant deferred maintenance
- Code violations or liens
- Property in declining neighborhood
- Value significantly below UPB
🚩 Borrower Concerns
- Pattern of broken payment promises
- Multiple modification failures
- Suspicious income claims
- Ongoing bankruptcy proceedings
🚩 Legal/Title Problems
- Senior liens or judgments
- Unpaid property taxes
- HOA liens or violations
- Unclear ownership or probate issues
For a comprehensive guide on identifying and avoiding problematic investments, read our detailed post: Note Investing Red Flags: What to Watch For
Due Diligence on the Paperstac Platform
Tired of chasing down documents and unclear ownership records? Paperstac streamlines the mortgage note due diligence process with built-in tools designed specifically for note investors.
How Paperstac Supports Your Mortgage Note Due Diligence Process
📁 Centralized Document Management
All critical documents—collateral files, payment histories, loan agreements, and assignments—are required from sellers and stored in one secure location. No more scattered emails, missing paperwork, or delayed responses. Both buyers and sellers access the same document repository, ensuring complete transparency.
✅ Verified Chain of Title
Paperstac's verified chain of title feature helps confirm notes have been properly transferred through documented assignments and endorsements. This systematic verification reduces the risk of title defects that could prevent foreclosure or impact your legal standing.
📋 Built-In Audit Trail
Every action is logged—document uploads, messages, signature requests, and communications. This creates a complete audit trail for your records and makes it easy to reference details during your review period or for future reference.
⏱️ Structured Transaction Timeline
The platform breaks the buying process into clear steps: document review, due diligence period, payment, and transfer. This structured approach prevents skipping critical steps and ensures both parties follow a professional timeline.
📚 Due Diligence Resources
Access educational resources through Paperstac Academy, including due diligence checklists, review templates, and guides that help you know exactly what to evaluate before making an offer.
💬 Efficient Communication
Ask questions, request missing documents, or clarify details directly within the platform. All communications stay organized within each transaction workspace, eliminating confusion and maintaining a clear record.
⚠️ Important Disclosure
Paperstac acts as a marketplace and technology provider that facilitates secure transactions between buyers and sellers. As an investor, you are responsible for conducting thorough due diligence on both the note and the seller.
Paperstac provides: Step-by-step transaction guidance, document management tools, third-party collateral verification services, escrow agent options, and extensive educational resources including Paperstac Academy and detailed due diligence checklists to help you make informed investment decisions.
Helpful Tips for Note Buyers
Essential Tips to Remember:
Remember that real estate-backed notes have underlying collateral to fall back on—unlike credit card debt or medical bills (unsecured debt).
Visual confirmation through BPO or drive-by prevents expensive surprises.
Ensure the notary who notarized previous Assignments had an active license (shown on the Notary Stamp).
Make sure there's a title policy with the collateral file. Verify the last person in the chain of title is the person selling you the loan.
Review the Owner & Encumbrance Report for county property tax issues.
Reach out to local real estate agents or order a BPO to confirm property value.
Every research step you take puts you in position to maximize profit at exit. Most due diligence steps focus on removing or mitigating risks that can't be completely eliminated.
💡 Key Principle: Risk Mitigation Through Research
Real estate note investments follow the classic real estate principle: you make money when you purchase, not when you exit. Every dollar spent on thorough due diligence protects your investment and increases profit potential. Rushed due diligence leads to costly mistakes that can eliminate returns or create losses.
Conclusion: Mastering Mortgage Note Due Diligence
Whether you're a note investor or own a note business, due diligence is crucial for success. This guide should increase your confidence as a note investor. With experience, the due diligence process becomes easier and more routine, allowing you to simplify the purchasing process once you master these fundamentals.
In conclusion, mortgage note due diligence is the foundation of successful note investing. By performing thorough due diligence, you minimize risks and make informed investment decisions. By following this guide and using our comprehensive Note Investing Due Diligence Checklist, you can gain confidence in your note investing decisions and increase your chances of success.
📋 Download Your Free Checklist
Want a printable version you can use for every deal? Download our comprehensive Note Investing Due Diligence Checklist to ensure you never miss a critical step in your evaluation process.
📺 Additional Video Resources
For more on running due diligence on mortgage notes, check out these helpful videos from the Paperstac YouTube channel:
📚 Related Resources
Frequently Asked Questions
What is mortgage note due diligence?
Due diligence is the process of evaluating a note before purchase to understand risk, borrower performance, property value, and legal enforceability. It's your essential risk assessment phase that protects your capital.
What happens if the borrower files bankruptcy during my foreclosure?
The automatic stay immediately halts your foreclosure. You must file a motion for relief from the automatic stay to continue. If the property has no equity or the borrower has no realistic ability to cure the default, courts typically grant relief within 30-60 days. However, this adds 1-2 months to your foreclosure timeline and $1,000-$3,000 in legal fees.
How do I know if there's an IRS lien on my property?
IRS liens are filed with the county recorder where the property is located. Your title search should reveal any recorded federal tax liens. You can also search online through some county recorder websites or request a Certificate of Lien from the IRS. Never assume there are no IRS liens—always verify during your title due diligence phase.
What's the difference between judicial and non-judicial foreclosure states?
Non-judicial states allow foreclosure without court involvement (typically 3-6 months, $1,500-$3,500 cost). Judicial states require filing a lawsuit and obtaining court judgment (typically 12-24+ months, $5,000-$15,000+ cost). The type is determined by your security instrument (deed of trust vs. mortgage) and state law—you cannot choose which method to use.
What are redemption rights and should I avoid redemption states?
Redemption rights allow borrowers to reclaim property after foreclosure by paying the full debt plus costs. About 26 states have redemption periods ranging from 30 days to 12+ months. Don't necessarily avoid these states—just factor the redemption period into your holding costs. A 6-month redemption adds significant costs (taxes, insurance, opportunity cost) that must be included in your purchase price calculations.
What documents do I need at closing to properly transfer the note?
Critical closing documents include: (1) Original promissory note with endorsement "without recourse", (2) Assignment of mortgage/deed of trust, (3) Title insurance policy or endorsement, (4) Complete payment history, and (5) Servicing transfer documents if applicable. The assignment must be recorded in the county where the property is located.
Why is due diligence essential when buying a note?
It protects your capital by helping you identify red flags, verify collateral, estimate true returns, and determine whether the note matches your buy box. Remember: you make money on the buy.
What are the main components of due diligence?
- Borrower review: payment history, behavior, communication
- Property analysis: value, condition, comps, taxes
- Collateral file review: chain of title, assignments, allonges
- Servicing data: payment history, balances, escrow
- Legal review: compliance, lien position, foreclosure status
- Financial modeling: yield, ROI, payback scenarios
What documents should I request in a collateral file?
- Original promissory note
- Mortgage/deed of trust
- Allonges
- Assignments
- Title policy
- Payment history
- Property information (BPO, appraisal)
- Servicer statements
- Compliance docs (TILA, RESPA, disclosures)
How do I evaluate borrower risk?
Look at several key factors:
- Payment history & consistency
- Communication responsiveness
- Hardship explanations
- Prior modifications or bankruptcies
- Current loan performance status (performing, sub-performing, non-performing)
How do I analyze the property securing the note?
Verify these critical elements:
- Current market value (via CMA, BPO, or comps)
- Property condition
- Neighborhood trends
- Occupancy status
- Senior lien status
- Tax status (delinquencies, liens, sales)
What is a BPO and why does it matter?
A Broker Price Opinion estimates the property value, providing context for your LTV, investment risk, and potential exit strategies. It gives you "eyes on the property" to prevent costly mistakes like purchasing notes secured by demolished properties.
How do I verify lien position?
Confirm through multiple sources:
- Title reports
- O&E (Ownership & Encumbrance) reports (approximately $90)
- County records
You must ensure you hold a first lien if the listing says so. Remember: tax liens take priority over mortgage liens.
What red flags should I watch for?
- Missing documents (note, assignments, allonge)
- Borrower non-communication
- Major tax liens
- Title defects
- Incorrect chain of title
- Low-value or distressed property
- Unrealistic seller pricing
- Recent borrower bankruptcy
How do I calculate expected yield or ROI?
Run different scenarios including:
- Payoff at purchase
- Payoff after reinstatement
- Modification and re-performance
- Foreclosure timeline + REO sale
You can use tools, spreadsheets, or pricing models available through Paperstac Academy.
What's the difference between performing and non-performing due diligence?
Performing notes: Focus on payment history, borrower stability, yield, and prepay risk.
Non-performing notes: Heavier emphasis on collateral, exit strategy, foreclosure laws, and property value.
How do I assess whether taxes are current?
Check multiple sources:
- County tax portals
- Title reports
- O&E reports
Unpaid taxes may require you to advance funds or can threaten the lien (especially for tax sales).
Should I order my own BPO or rely on the seller's?
Always verify with your own research, comps, or third-party BPO. Seller valuations can be outdated or optimistic. Use resources like Zillow, Realtor.com, Redfin, and consider services like Proxy Pics for visual confirmation.
How do I evaluate the servicing notes?
Review the servicer comments for:
- Borrower communication
- Hardship discussions
- Collection attempts
- Status updates
- Bankruptcy issues
Servicing notes are often the most honest picture of the borrower's behavior and provide context that raw payment data cannot.
How do I check the foreclosure status?
Use multiple sources:
- County court records
- Servicer notes
- Status updates from the attorney
- Public notices
This helps estimate cost and timeline if foreclosure becomes necessary. Remember that judicial states like New York and New Jersey can take 2-3 years.
What is chain of title and why is it important?
It proves that every transfer of the note and mortgage was properly recorded. Breaks in chain can delay foreclosure and reduce the enforceability of your note. Always verify complete assignments from originator to current holder.
What is an allonge?
An allonge is an attachment used when there is no space left on the promissory note for endorsements. Missing allonges can be a legal issue and may require a lost note affidavit, which can complicate or delay foreclosure proceedings (and is impossible in Maine).
Do I need an attorney for due diligence?
For non-performing notes and judicial states, yes—an attorney can help assess foreclosure timelines, title issues, and risk. Even for performing notes, legal review can identify compliance issues that might become problems later.
How do I determine the right offer price?
Base it on multiple factors:
- Current LTV
- Property value
- Borrower behavior
- Foreclosure timeline
- Expected exit strategy
- Your required yield
- Repairs or taxes owed
Remember: You're pricing risk, not just numbers. A 65-75% LTV is typically ideal for balanced risk and return.
What are common exit strategies with notes?
- Reinstatement & modification
- Payment plan
- Reperformance
- Foreclosure → REO sale
- Deed in lieu
- Selling the note
- Full loan payoff
What is collateral?
The real property (house or land) securing the note. Due diligence ensures the collateral has enough value to justify the investment and protect your downside risk if the borrower defaults.
How do I check if the loan was originated legally?
Review TILA (Truth in Lending Act), RESPA (Real Estate Settlement Procedures Act), and state-required disclosure forms. Missing disclosures can become defenses for borrowers in legal proceedings and may delay or prevent foreclosure.
How do bankruptcy filings change due diligence?
You must check PACER (Public Access to Court Electronic Records) for:
- Chapter 7 or 13 filing
- Automatic stay
- Plan payments
- Discharge status
Bankruptcy dramatically affects timeline and strategy. Active bankruptcy requires working through the bankruptcy court system.
What should I verify about the seller?
- Is the seller reputable?
- Do they provide complete files?
- Are they responsive?
- Is the price aligned with market norms?
Working with trusted sellers (like Paperstac Power Sellers) lowers risk and ensures better document quality.
📄 Download Our FREE Intro to Note Investing Guides from Paperstac Academy👇
Get a taste of the exciting world of note investing with our FREE Note Investing Guides.
