
Ideas for a better investment
Senior-Lien Checks: How Note Buyers Avoid a Total Loss
Senior lien checks reveal claims LTV and payment history can't. How note buyers catch tax liens and HOA super-liens before they cost you.

13 min read
By Elena Novak, PropertyChecker.com • Edited by Jessica Gold, Paperstac
Key Takeaways
- Lien position is the risk most checklists overlook. LTV, payment history, and property value describe the asset — none of them reveal who else has a claim on it.
- Lien priority generally runs on a “first-in-time, first-in-right” basis, but tax liens and, in many states, a portion of HOA liens can leapfrog to the front regardless of when they were recorded.
- A full record check covers four things: a title search or O&E report, the senior mortgage and assignment chain, tax liens, and HOA/COA liens.
- In 2025, HOAs filed 284,933 liens nationwide — up 8.6% from 2024, roughly one every 90 seconds.
- In roughly 20 states plus D.C., HOA “super-lien” laws let a portion of unpaid dues jump ahead of even a first mortgage.
- An O&E report is a faster, cheaper alternative to a full title search — typically $75–$200 — for a quick read on junior-lien risk.
You’ve heard the worst-case scenario: a note secured by a desirable property clears every standard check. The LTV looks fine, the payments are current, and the property value is solid. Yet the loan loses most of its value because a senior mortgage, tax lien, or HOA lien sits ahead of it. Lien position is the risk most due diligence checklists overlook — and it’s the one that can turn a clean-looking note into a total loss.
LTV, payment history, and property value all describe the asset. None of them tell you who else has a claim on the property or who holds senior priority. In most states, lien priority runs on a “first-in-time, first-in-right” basis: the senior lien gets paid first, and a junior lienholder is paid last — often receiving nothing when the property sells in foreclosure. This isn’t a rare edge case. It’s a real, quantifiable risk, and it’s one you can check for before you bid.
Quick answer
To avoid a total loss from a hidden senior claim, note buyers run four record checks before bidding: a title search or O&E report for the chain of title, verification of the senior mortgage and assignment chain, a check for tax liens (which often carry “super-priority” status), and a check for HOA or COA liens. In roughly half the country, HOA super-lien laws let a portion of unpaid dues jump ahead of even a first mortgage — so lien position, not just LTV or payment history, determines what you’d actually recover if a note goes bad.
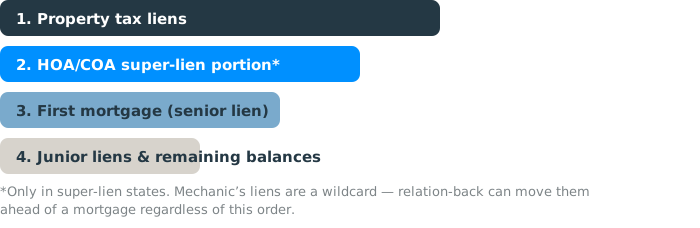
A simplified view of typical lien priority — actual order depends on state law, recording dates, and the specific liens involved.
The Record Checks That Reveal Hidden Claims
The importance of lien position for note buyers cannot be overstated. Use the sequence below to cover the record checks needed to reveal hidden claims and liens that could affect your position.
1. Order a Title Search or O&E Report
A full title search is a deep dive into historical property records, usually going back 30 to 40 years, with the goal of establishing a clear chain of title. It can uncover past title defects, old unreleased easements, historical ownership transfers, boundary issues, and more.
O&E report: An Ownership and Encumbrance report is a streamlined, narrower version of a title search that typically tracks records only from when the current owner acquired the property to the present. Real estate investors, foreclosure buyers, and wholesalers rely on O&E reports for a quick snapshot of junior-lien risk — typically $75–$200, depending on the vendor.
2. Confirm the Senior Mortgage and Assignment Chain
Checking for senior liens and mortgage issues means searching the county’s land records. This involves three essential steps:
- Verify the senior lien. Priority is almost always determined by “first in time, first in right” — the mortgage recorded earliest has priority. Pull the current deed to verify ownership and the starting date of the owner’s title, then search the grantor/grantee index from that date forward, listing all open mortgages by recording date and time (not signing date). Watch for subordination agreements, which can voluntarily push an older lien behind a newer loan.
- Check for unreleased or unrecorded mortgages. An unreleased mortgage clouds the title; an unrecorded one is a hidden risk. For every mortgage you find, search for a corresponding satisfaction, release of lien, or deed of reconveyance. No matching release means it’s legally still “open.” You can’t directly find an unrecorded mortgage in county records, but you can spot signs of one. Look for subordination agreements referencing a loan you don’t see on record, or modifications and lien notices citing a loan number that doesn’t match anything documented.
- Read the assignment chain for gaps. When a mortgage is sold between lenders, it moves via an assignment of mortgage. A “gap” occurs when the chain of ownership breaks — for example, if Bank B became Bank C through a merger and no physical assignment was recorded. Checking banking regulatory sites (the Federal Reserve or OCC) can confirm whether it was a legal name change or acquisition.
3. Check for Tax Liens
Tax liens deserve special attention because they typically carry super-lien priority — outranking even a first mortgage. Property tax information is generally available through the county tax assessor/collector or the county clerk/recorder of deeds, often via online portals.
Depending on the state, the county may sell the lien to private investors through a tax lien sale, or foreclose after a set period. Because tax liens fund essential services like schools, police, and fire departments, most states grant them automatic super-priority status — jumping ahead of a first mortgage recorded years earlier, regardless of when the tax lien itself was filed.
4. Check for HOA/COA Liens
Homeowners’ and condominium owners’ associations can place a lien on a unit for unpaid fees or special assessments. These liens are easy to miss: in some states, no formal recording is required, and the lien becomes active the moment the debt goes overdue — though most HOAs do eventually record it with the county clerk.
Check county land records for documents like an assessment lien, claim of lien, or notice of delinquent assessment, and verify whether a release or satisfaction was later filed. If you suspect an HOA lien but find nothing recorded, contact the HOA or its management company directly and request an estoppel certificate or payoff letter.
HOA liens filed nationwide in 2025 — up 8.6% from 2024, roughly one every 90 seconds. Florida alone accounted for 17.4% of the national total. (Benutech, via HousingWire)
Super-Lien States: Where Even a Senior Note Holder Can Lose
State law dictates lien priority. In certain states, statutes let a portion of an HOA/COA lien — commonly capped at a set number of months of assessments or a dollar amount — jump ahead of even a first mortgage’s priority. That means a note buyer who confirmed they’re in first position on title can still lose part of their recovery to an HOA lien.
Nevada is a clear example: its super-priority cap covers nine months of assessments under NRS 116.3116. At the state’s roughly $380 average monthly due, that’s about $3,420 the HOA collects off the top before the senior lienholder sees a dime — and with larger special assessments, that figure can grow further.
Roughly 20 states plus the District of Columbia have some form of HOA/COA super-lien provision, including Florida, Massachusetts, Nevada, Pennsylvania, and Vermont. Super-lien states are exactly why the record checks above need to include HOA/COA status, not just the senior mortgage.
A Note That Looked Clean and Wasn’t
A real case shows exactly how this plays out: In Commerce Bank v. Kessler (Pa. Super. Ct. 2012), a couple took out a construction loan secured by a mortgage to build a home on their property. Excavation had already begun before the mortgage was recorded a few months later.
When the loan defaulted, the question became which claim had priority: the bank’s recorded mortgage, or the contractor’s mechanic’s lien. The court ruled for the contractor. The loan proceeds weren’t used solely for direct “hard” construction costs — some went to closing costs and fees. Because construction had physically started before the mortgage was recorded, the mechanic’s lien related back to the earlier date and took priority. The bank’s recorded first position didn’t protect it.
Standard LTV and payment-history screening wouldn’t have caught this — recent construction activity and how loan proceeds are actually used are exactly the kind of detail a title and lien check is designed to surface.
FHA-backed loans originated in 2023 that also carry at least one small subordinate lien — roughly $880 million in additional obligations that wouldn’t show up in standard LTV or payment-history screening. (Benutech, via HousingWire)
LTV & Payment History vs. Lien and Title Checks
These two categories of due diligence look at completely different things — which is exactly why relying on only one leaves a gap.
| Feature | LTV & Payment History Check | Lien & Title Check |
|---|---|---|
| Primary focus | Borrower financial behavior & equity cushion | Legal ownership & encumbrances against the property |
| What it catches | Missed or late payments; outstanding balances; high LTV; patterns of financial distress | Unpaid taxes & HOA super-liens; mechanic’s liens; judgment liens; IRS or state tax liens |
| Legal issues caught | None — doesn’t evaluate legal title or priority | Chain-of-title defects; conflicting priority claims; easements or encroachments |
| Who performs it | Underwriters, mortgage lenders, or servicers | Title companies, real estate attorneys, or abstractors |
Also on the Paperstac blog: Paperstac’s mortgage note due diligence checklist covers the full pre-purchase process.
A Pre-Bid Lien-Check Workflow
The hidden risk of note purchasing is priority. Use this sequence to cover your bases before you commit.
- Order an O&E report. Before or just after bidding, review the chain of title and look for ownership issues.
- Audit senior priority. Use a title search to check for senior lien priority, unreleased mortgages, signs of an unrecorded mortgage, and gaps in the assignment chain if the mortgage was sold or transferred between lenders.
- Check local tax status. Search county records for tax liens and potential foreclosure activity.
- Request an HOA estoppel certificate. Review county records for HOA/COA liens, or contact the management company directly for an estoppel certificate or payoff letter confirming the lien has been resolved.
Buying on Paperstac? See questions to ask before buying a mortgage note for the borrower- and payment-side checks that pair with the lien and title review above, or brush up on the underlying documents in what is a promissory note and what is a deed of trust.
Key Terms to Know
A few terms come up throughout this process — here’s what each one actually means.
Lien position
Where a claim ranks in line to be paid from a property’s sale or foreclosure proceeds. First position (senior) gets paid before second, third, and so on.
Chain of title
The complete, unbroken history of who has owned or held a claim on a property, traced through recorded deeds, mortgages, and assignments.
Super-lien
A lien — typically for taxes or, in some states, HOA/COA dues — that state law lets jump ahead of a first mortgage’s priority, regardless of when it was recorded.
Mechanic’s lien
A claim filed by a contractor or supplier for unpaid work or materials. In many states, its priority “relates back” to when work physically began, not when it was recorded.
Estoppel certificate
A written statement from an HOA (or lender) confirming the current amount owed on an account — used to verify a lien has been paid off or to get an accurate payoff figure.
Subordination agreement
A signed agreement in which a lienholder voluntarily agrees to move their claim into a junior position behind a different lien.
Frequently Asked Questions
What is lien position and why does it matter for note buyers?
Lien position determines who gets paid first if a property is sold or foreclosed. A senior lien is paid before a junior one, and a junior lienholder can receive little or nothing. LTV, payment history, and property value don’t reveal lien position — only a title or lien search does.
What’s the difference between a title search and an O&E report?
A full title search traces ownership back 30–40 years to establish a complete chain of title. An O&E (Ownership and Encumbrance) report is narrower, typically covering only the period since the current owner acquired the property. O&E reports are faster and cheaper ($75–$200) and are often used for a quick read on junior-lien risk.
Why do tax liens outrank even a first mortgage?
Most states grant property tax liens automatic “super-priority” status, meaning they jump ahead of the standard first-in-time, first-in-right rule — even ahead of a mortgage recorded years earlier. This reflects that property taxes fund essential public services.
What is an HOA super-lien?
In roughly 20 states plus D.C., state law lets a portion of an HOA or COA’s unpaid-assessment lien — often capped at a set number of months or a dollar amount — take priority over even a first mortgage. Nevada’s cap, for example, is nine months of assessments. A note buyer in confirmed first position can still lose part of their recovery to a super-lien.
How common are HOA liens?
HOAs filed 284,933 liens nationwide in 2025 — up 8.6% from 2024, or roughly one every 90 seconds, according to Benutech data reported by HousingWire. Florida accounted for 17.4% of the national total.
Can an unrecorded mortgage really exist?
Yes, and by definition you can’t find one directly in county records. Signs to watch for include a subordination agreement referencing a loan that isn’t on record, or a modification or lien notice citing a loan number that doesn’t match any documented mortgage.
How do I check for a mechanic’s lien before buying a note?
A title search or O&E report should surface a recorded mechanic’s lien. But in many states, a mechanic’s lien’s priority relates back to when work physically began, not when it was recorded — meaning it can outrank a mortgage recorded before the lien itself appeared in county records. Recent renovation activity on a property is worth asking about directly.
Do I need a lien and title check if the LTV and payment history already look good?
Yes. LTV and payment history evaluate the borrower’s financial behavior and the asset’s equity cushion — they say nothing about legal title or competing claims. A note can pass both checks cleanly and still carry a hidden tax lien, HOA super-lien, or mechanic’s lien that erodes your actual recovery.
Learn the Full Due Diligence Process
Paperstac Academy breaks down title, lien, and collateral file review with real case studies and document tools, guided by CEO Rick Allen and hundreds of closed transactions.
Explore Paperstac AcademyKeep Learning
Related resources from the Paperstac blog.
Sources & References
- National Association of REALTORS®. 2025 Deed & Title Fraud Survey. nar.realtor
- HousingWire / Benutech. HOA liens climb 8.6% in 2025 as Sun Belt pressure mounts. housingwire.com
- HousingWire / Benutech. Hidden liens on 2023 FHA loans. housingwire.com
- Nevada Revised Statutes § 116.3116 (HOA super-priority lien).
- Nolo. Homeowners’ Association Super Liens (updated Aug. 2025). nolo.com
- First American Data & Analytics. What Are Super Lien States? Why HOA Data Matters. dna.firstam.com
- Buchanan Ingersoll & Rooney PC. A Question of Priority: Court Ruling Bumps Mortgage in Favor of Mechanic’s Lien (analysis of Commerce Bank v. Kessler, Pa. Super. Ct. 2012). bipc.com
This article is for educational purposes only and does not constitute legal advice. Lien priority rules vary significantly by state and change over time. Always perform your own due diligence and consult a qualified real estate attorney and title professional before buying, selling, or investing in a note. © 2026 Paperstac.